What you'll learn
Key ideas from The Ascent of Money
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
Money serves exchange, accounting, and saving when people share confidence in its use and in the institutions that honor payment.
Fractional-reserve lending turns deposits into additional spendable balances, while rapid withdrawals can reverse that expansion.
Florence and Britain show that sovereign credit rests on political arrangements as well as written promises.
Inflation becomes catastrophic when monetary expansion combines with fiscal weakness and political conflict; monetary growth alone does not explain national differences.
Joint-stock companies pool capital for long ventures, while tradable shares make prices a continuing judgment about future prospects.
Actuarial insurance uses group records and invested premiums to fund recurring claims, although individual outcomes remain uncertain.
Public guarantees expanded mortgage access, while securitization separated loan approval from the investors who bore losses.
LTCM’s leverage magnified losses when volatility rose, markets moved together, and recent data failed to represent crisis conditions.
Inside The Ascent of Money
Read the first chapter in full here. The other 8 continue in the Wiseley app.
Chapter 1 of 9 · 9 min · Audio & text
Money as Trust and Promise
The Ascent of Money, by Niall Ferguson.
What makes money valuable: the substance it is made from, or the willingness of others to accept it? Niall Ferguson’s history points to a social answer. Money works when people trust that they can use it in exchange, count value through it, and preserve some claim for later. Metal can carry that promise, but metal alone cannot explain why people accept one coin and reject another, or why a paper note can be worth more than the paper itself.
Money is often described by three functions: a medium of exchange, a unit of account, and a store of value. These functions do not require that every society use coins or notes. Some societies organized life without money. The Inca Empire, for example, valued gold and silver for their appearance, but treated labor as its unit of value. Its sophisticated organization relied on harsh central planning and forced labor. Moneyless life should not be mistaken for a universally peaceful or equal alternative; nor does the existence of money make every society fair.
Records from ancient Mesopotamia show that monetary life could be built around promises as well as objects. Clay tokens and tablets recorded exchanges involving produce and metals. A tablet from Sippar promised its bearer barley at harvest; another promised silver when a journey ended. Such a record made a future obligation legible: someone was to deliver a specified amount, at a specified time. The clay did not contain the barley or silver. Its value depended on people recognizing the claim it represented.
These records also reveal the close connection between money and credit. Lenders kept tablets that set out what had been borrowed and when repayment was due. Babylonian lending could include interest and debts that passed from one holder to another. Lending depended on a belief that the borrower would repay, and on some means of recording or enforcing the obligation. The surviving records of the Egibi family, a powerful group of landowners and lenders, show how many such claims could accumulate across generations.
This early evidence needs a qualification. Most Babylonian loans were advances from royal or religious storehouses. They were not credit creation in the modern sense. The point is not that ancient lenders already operated like contemporary banks. It is that the basic relationship behind credit—one party transfers something now in return for a promise of repayment later—was already familiar. The record helped make the promise specific, but trust in the borrower and the surrounding institutions still mattered.
Money’s form can change while this social basis remains. A banknote, like an ancient tablet, can stand for a claim whose worth exceeds the material carrying it. A note has little use as paper alone. People accept it because they expect others to accept it in turn, and because they trust the issuer and institutions behind payment. Money may be silver, clay, paper, or an electronic balance; in each case, its practical value rests on shared confidence that it will be recognized and usable.
In 1545, an Indigenous man named Diego Gualpa discovered the five great seams of silver in Cerro Rico, Upper Peru. The mountain held metal that could be transported, stored, and counted. For the Spanish, silver was not merely decoration. It could serve as a unit of account and a store of value, and it could carry purchasing power across long distances. The mountain that gave rise to Potosí became a source of wealth for the Spanish crown and a turning point in the movement of money around the world.
That wealth was extracted through coercion. Spanish mining initially used wage labor, but the late-sixteenth-century mita conscripted Indigenous men from highland provinces for seventeen weeks each year. The work involved toxic mercury, dangerous air, arduous access, and the risk of rockfalls. Many workers suffered injury or died. As the Indigenous workforce declined, enslaved Africans were brought in as replacements. The silver’s value to distant rulers and merchants rested on a brutal system of labor imposed on people with little choice in it.
Between 1556 and 1783, Cerro Rico yielded 45,000 tons of pure silver. Potosí grew into a major imperial city, while shipments crossed the Atlantic to Spain. The crown reserved a fifth of production. The Spanish piece of eight, made from this silver, became a global currency and helped finance the empire’s wars and trade with Asia. Silver brought the crown real revenue and gave merchants a widely accepted means of payment. It did not, however, guarantee lasting political power or prosperity for everyone connected to the system.
A plentiful supply can weaken the purchasing power of money. As silver became more abundant, each unit bought less. The influx helped drive Europe’s price revolution from the 1540s to the 1640s; in England, the cost of living rose sevenfold. More silver could enrich the government that controlled the mines and shipments, but that did not mean society as a whole had become richer. If the quantity of money rises faster than the goods people can buy, prices can rise and the money’s purchasing power can fall.
Ferguson also describes Spain’s silver as a resource curse. A steady flow of wealth from the mines reduced incentives to build other productive activities and strengthened rulers able to capture the revenue. Silver could fund power, but it could not ensure that power was used to develop a durable economy or representative institutions. The example separates the source of a currency’s material supply from the institutions and choices that shape its effects.
The lender’s side of a promise comes into focus in Shakespeare’s Merchant of Venice. Bassanio borrows three thousand ducats from Shylock, with Antonio guaranteeing repayment. Shylock calls Antonio a good man because his credit is sound, not because he is morally virtuous. Yet Antonio’s wealth is tied up in ships traveling distant routes, exposed to weather, pirates, and other hazards. His apparent means do not make repayment certain. The risk of lending to merchants helps explain why a lender might charge interest: the payment compensates for the possibility that the promise will not be kept.
The play’s bond also sits within a particular religious and legal setting. Christian teaching condemned lending at interest as usury, while Jewish lenders in Venice could lend to Christians under a different interpretation of religious rules. For nearly a century, Jewish lenders provided commercial credit in the city. Their work took place under social restrictions: they were confined to the ghetto and barred from guilds and retail trade. Their access to financial work did not mean their rights were secure. Authorities could make their privileges conditional or threaten to revoke them.
In the play, the court recognizes Shylock’s bond but prevents him from taking the pound of flesh. Because he is treated as an alien who plotted against a Christian, he faces the loss of his property and life, and escapes that fate only through baptism. This is a literary episode, not a simple record of how every debt case worked. It shows a lender with a written claim, a court that determines what the claim permits, and a creditor whose standing is vulnerable to the power of the majority. Law can make promises enforceable, but its protection may not be equal for everyone.
Together, the tablets, Potosí silver, and Shylock’s bond suggest a practical question for any monetary system: who trusts whom, on what promise, and who bears the loss if it fails? Money can make exchange and lending possible across time and distance. Its consequences depend on who can issue or enforce claims, whose labor supports them, and whose interests the law protects.
Chapter 2 of 9 · 10 min · Audio & textIn the app
Banking, Reserves, and Credit
Credit moves from a promise between two people to a system when lending can be repeated and monitored. Each small loan costs time: a lender must assess the borrower, record the terms, and collect repayment.
Chapter 3 of 9 · 8 min · Audio & textIn the app
Government Bonds and State Power
A government facing the cost of war may need money before taxes can cover the bill. One way to raise it is to sell a bond: a transferable promise to pay interest.
Chapter 4 of 9 · 10 min · Audio & textIn the app
Inflation, Default, and Discipline
Public debt distributes wealth as well as paying for government. In early nineteenth-century Britain, interest on the national debt took about half of public spending, while more than two-thirds of tax revenue came from indirect taxes on consumption.
Chapter 5 of 9 · 13 min · Audio & textIn the app
Shares, Bubbles, and Belief
A joint-stock company makes it possible to gather money from many investors for ventures that would be too large or risky for one person or a small partnership. Each investor owns shares, and the company can use the pooled capital for projects that may take years to earn a return.
Chapter 6 of 9 · 12 min · Audio & textIn the app
Insurance and Shared Risk
People have always tried to prepare for bad luck. A community might store food against a poor harvest, or neighbors might contribute to a burial society so a family could afford a funeral.
Chapter 7 of 9 · 12 min · Audio & textIn the app
Homes, Debt, and Ownership
A house can be shelter, wealth, collateral, and a claim to a place in society. Those roles do not always line up.
Chapter 8 of 9 · 13 min · Audio & textIn the app
Global Capital and Fragility
Before 1914, international finance was already deeply connected. Investors could buy government bonds and railway securities across continents, while faster communications and gold convertibility made distant investments easier to manage.
Chapter 9 of 9 · 7 min · Audio & textIn the app
Uncertainty and Financial Evolution
The history traced in this book presents finance as both a source of prosperity and a recurring source of danger. Banks and markets can move resources toward productive uses, and new financial forms can widen the ways people borrow, invest, and share risks.
Chapter 1 of 9 · 9 min · Audio & text: Money as Trust and Promise
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyWhat The Ascent of Money is about
How did money become a force that builds societies and also makes them vulnerable? Niall Ferguson traces the history of credit, banks, bonds, shares, insurance, property, and global capital, showing how financial systems widen opportunity while shifting risk and power. The account helps listeners read debt, financial shocks, and the limits of prediction.
About Niall Ferguson
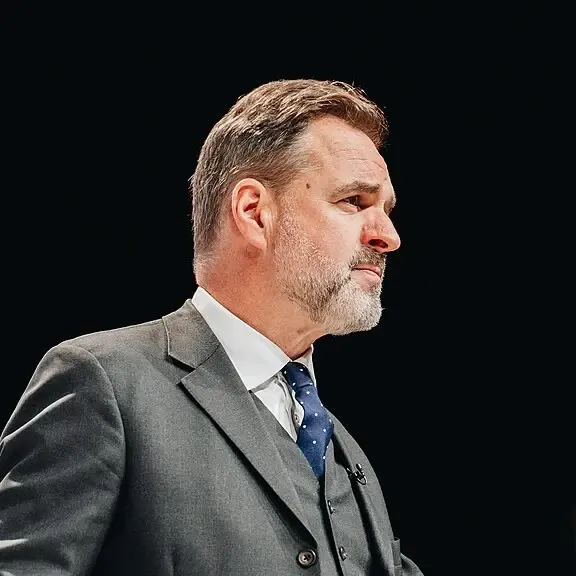
Niall Ferguson is a Scottish historian. “The Ascent of Money” explores how credit, banks, bonds, shares, insurance, and property built societies and also made them vulnerable.
Explore more books by Niall Ferguson