What you'll learn
Key ideas from Super Founders
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
A characteristic common among winners matters only when its prevalence and classification are compared with the baseline.
Prior company-building is the strongest reported founder distinction because operating skills, judgment, and relationships can accumulate across attempts.
Effective pivots question the original premise, validate actual demand, and preserve team communication and cash for execution.
Market opportunity combines real demand, reachable distribution, and conditions that make adoption possible; first-mover status alone is insufficient.
Defensibility grows when technical, network, data, partnership, brand, or scale advantages reinforce one another, though every moat can be overcome.
Funding should match capital needs, speed, desired scale, ownership preferences, and the investor’s capabilities.
Runway discipline combines burn scenarios, company-wide budget scrutiny, and spending choices that preserve cash while improving economics.
Fundraising is a sequence of customer proof, team strength, targeted relationships, and milestones that reduce specific business risks.
Inside Super Founders
Read the first chapter in full here. The other 10 continue in the Wiseley app.
Chapter 1 of 11 · 5 min · Audio & text
Reading Startup Evidence Without Mythmaking
Super Founders, by Ali Tamaseb.
Super Founders begins with a simple question: when a startup becomes famous, are we learning a real pattern, or merely repeating a memorable story? The author compares more than two hundred startups that reached billion-dollar valuations with a separate group of two hundred startups. Across roughly thirty thousand data points and more than sixty-five factors, he examines founders, companies, markets, competition, defensibility, investors, and fundraising. The aim is to replace vivid anecdotes with broader evidence. It is also to show where the evidence stops.
The comparison group is essential. The two hundred companies in the baseline were randomly sampled from roughly twenty thousand startups founded between 2005 and 2018 that had raised at least three million dollars. That makes the baseline a useful reference point, but not a census of every business or every kind of startup. If a characteristic appears frequently among billion-dollar companies, that frequency means little by itself. We need to know how often the same characteristic appears elsewhere. A trait shared by nearly all winners may be distinctive, or it may simply be common among startups in general.
This is why the book keeps separating association from explanation. Suppose many successful founders share a particular background. The data can show that the background is associated with the outcome. It cannot, on its own, show that the background caused the company to succeed. Other factors may be involved, including prior experience, access, privilege, luck, or conditions that were not measured. A comparison with the baseline helps expose that problem, but it cannot remove every source of uncertainty.
The author also explains how statistical caution works in plain terms. A ninety-five percent confidence interval places a visible band around an estimate, reminding us that a reported percentage is not perfectly exact. The study examines many factors, though, and testing many differences creates a further danger: some results will look meaningful by chance. To limit these false discoveries, the author says he used the Benjamini-Hochberg procedure and focused attention on the strongest differences. Statistical controls do not turn an observational study into a prediction machine. They make its patterns more disciplined to interpret.
The definition of success needs the same care. The book uses a billion-dollar valuation because it is a measurable threshold, often based on private investor valuations. That threshold is convenient for comparison, but it is still an arbitrary proxy. A company can reach it and later lose its unicorn status. Valuation does not directly tell us about revenue, profit, durability, or social impact. In other words, crossing the line is evidence that investors assigned a certain value at a certain time. It is not a complete account of whether the business became a lasting achievement.
The study is retrospective: researchers look at companies whose outcomes are already known and then examine what their founders and businesses had in common. That design can reveal recurring patterns, but it also brings risks. Failed companies may disappear from the lists researchers can find. Records may be incomplete, founders may later rewrite their histories, and manual classification can involve judgment, especially when identifying competitors or forms of defensibility. The analysis cannot fully normalize differences in luck, privilege, and access.
Interviews add texture, but they are not the same as statistical evidence. Some interviewees resemble the broader dataset; others are outliers. Those outliers are useful because they show that a company can succeed despite an unfavorable pattern, but they do not overturn the overall comparison. They illustrate possibilities rather than establish general rates.
A practical way to read the rest of the book follows from this framework. First, identify the comparison group. Second, ask how the variable was defined and classified. Third, ask whether the evidence shows association or a causal explanation. Read each finding as a clue about recurring conditions, not as a formula for choosing an individual founder or predicting one startup’s future. Comparative evidence can challenge startup folklore without promising certainty about any particular company.
Chapter 2 of 11 · 7 min · Audio & textIn the app
Replacing Founder Stereotypes With Team Judgment
Founder stereotypes offer a convenient checklist: young, technical, a dropout, educated at a famous university, and paired with the right cofounder. Super Founders points elsewhere.
Chapter 3 of 11 · 9 min · Audio & textIn the app
How Building Experience Compounds
Once the book has cleared away simple founder stereotypes, it asks what preparation can actually accumulate. Its answer is a record of building, not age, degrees, or a fixed technical profile.
Chapter 4 of 11 · 7 min · Audio & textIn the app
Finding Demand Through Deliberate Adaptation
A startup does not have to begin with a founder’s personal frustration. The book describes deliberate searching, market observation, academic work, and projects inside established companies.
Chapter 5 of 11 · 9 min · Audio & textIn the app
Designing Value and Operating Fit
Once a founder has found a promising need, another design problem begins: fit. It has two sides: the environment where the company can operate, and the value customers will recognize.
Chapter 6 of 11 · 8 min · Audio & textIn the app
Choosing Markets at Their Inflection Points
Market opportunity is not simply a question of arriving first. In the book’s comparison, more than 60 percent of billion-dollar companies began where demand was already established, versus 47 percent of the random startup group.
Chapter 7 of 11 · 8 min · Audio & textIn the app
Winning Entry and Building Defensibility
Competition is not one kind of obstacle. In the book’s sample, fifty-five percent of billion-dollar startups faced multiple large incumbents; seventeen percent had no competition; fifteen percent entered fragmented markets; and thirteen and a half percent competed only with startups at founding.
Chapter 8 of 11 · 7 min · Audio & textIn the app
Matching Capital to Company Ambition
Financing is a choice about how a company operates, not merely how it pays its bills. Venture capital brings outside money in exchange for ownership and is built around exceptional scale.
Chapter 9 of 11 · 6 min · Audio & textIn the app
Turning Financial Constraints Into Discipline
Financial constraints do not affect a startup only by tightening its own budget. In a downturn, investors become cautious, valuations fall, and funding contracts.
Chapter 10 of 11 · 6 min · Audio & textIn the app
Choosing Investors as Working Partners
Once investors enter a company, they do more than supply cash. They bring judgment, access, expectations, and sometimes formal power.
Chapter 11 of 11 · 9 min · Audio & textIn the app
Raising Money Through Demonstrable Progress
Fundraising works best when it finances demonstrable progress instead of prestige, speed, or the appearance of certainty. Start with a clear explanation: who is the customer, what problem matters, what value the product creates, and why the timing is right.
Chapter 1 of 11 · 5 min · Audio & text: Reading Startup Evidence Without Mythmaking
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyWhat Super Founders is about
What distinguishes billion-dollar startup founders from other entrepreneurs? Ali Tamaseb compares company histories and founder interviews to challenge familiar stereotypes and examine experience, product differentiation, markets, and financing. The resulting patterns offer founders and investors a framework for judgment while preserving the limits of retrospective evidence.
About Ali Tamaseb
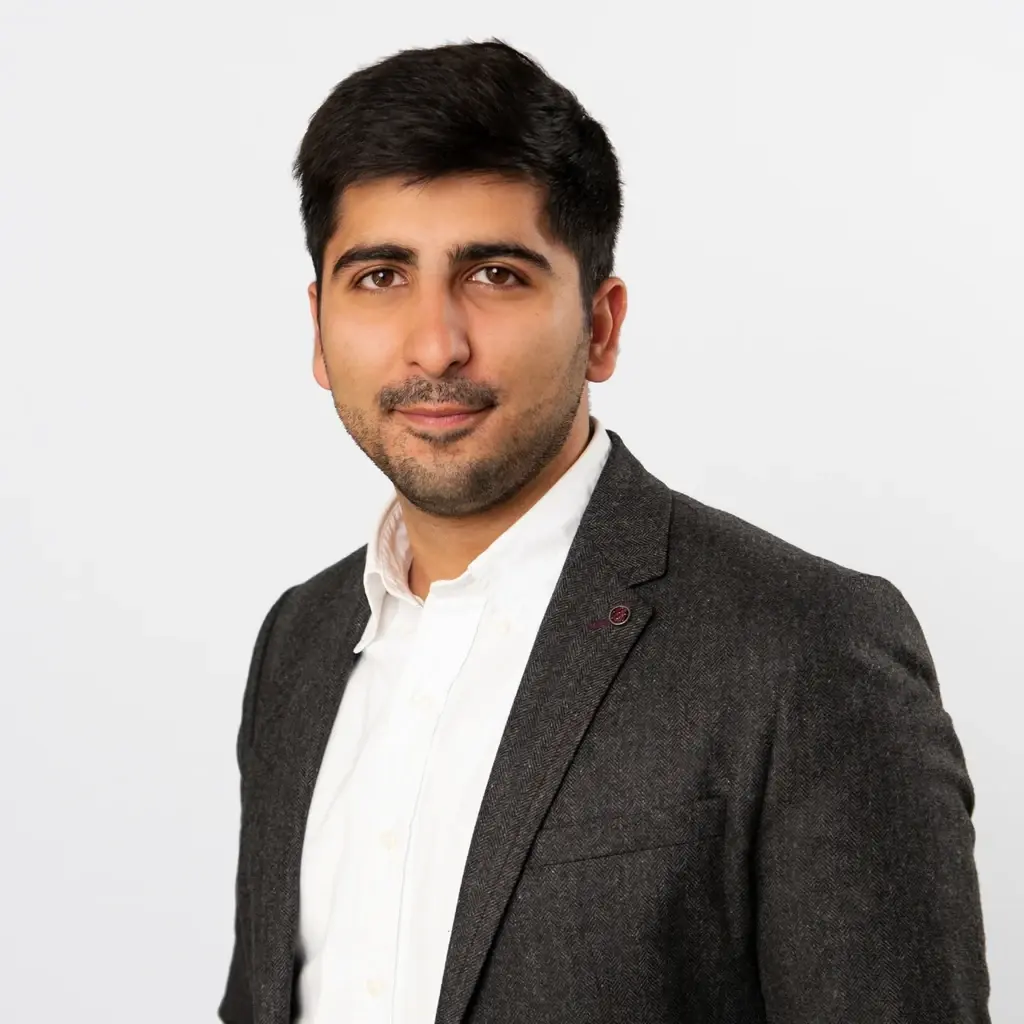
Ali Tamaseb is the author of “Super Founders”. The book explores what the data on billion-dollar startups reveals about their founders, products, markets, and funding.
Explore more books by Ali Tamaseb