What you'll learn
Key ideas from Money
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
Wealth includes financial resources and personal assets such as skills, relationships, knowledge, and service.
Vision links financial aims with purpose, contribution, and legacy, and can give strength through difficult changes.
Moore’s wealth formula combines useful value and fair exchange with leverage that distributes delivery more widely.
Selling is service under fair exchange: it begins with understanding a need and offering a solution that fits.
Small customer tests make demand, product improvements, and pricing assumptions visible before a larger launch.
Automated money buckets and reserves place saving and stability ahead of unfamiliar or speculative risk.
Net worth, capital relative to assets, spending relative to income, and months of living costs covered reveal different parts of financial progress.
Inside Money
Read the first chapter in full here. The other 12 continue in the Wiseley app.
Chapter 1 of 13 · 6 min · Audio & text
Money, Opportunity, and Change
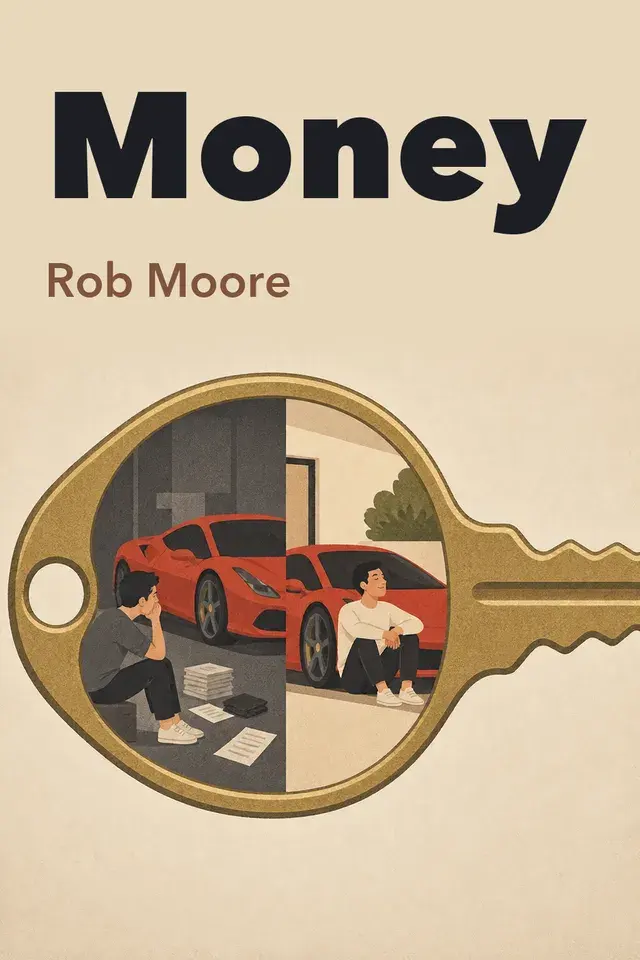
Money, by Rob Moore.
Money is more than a balance in an account. In Moore’s opening, it is also something people interpret through experience, beliefs, and emotion. Those interpretations can shape what they notice, what they assume about others, and which possibilities seem open to them. Moore sets out to question those assumptions and to look at how changing economic and financial systems create opportunities. His starting point is personal: a judgment he made while deeply in debt, and how buying that same model later made him reconsider his earlier judgment.
As a young man, Moore saw a Ferrari he had long admired. At the time, he was in substantial debt and felt bitter and envious. He called the driver a drug dealer, turning an unknown person into a story that matched his own feelings about money. Later, he recognized that he had no basis for the accusation. The driver might have been a drug dealer, a dentist, therapist or philanthropist. He could also have been a salesman giving the car a run before a test drive with someone like Moore. Moore says the judgment revealed more about his own outlook than about the stranger. After his circumstances changed, he bought the same model. The contrast illustrates how financial strain can distort perception—and how visible wealth alone tells us little about a person.
Moore uses that experience to introduce a distinction between hardship in a developed country and the unequal access to opportunity faced by people in the third world. Someone may feel poor in comparison with people who have more, while still living with the security, amenities, and internet access that Moore associates with abundant opportunity. This does not make relative hardship imaginary; it highlights that people face different constraints and unequal starting points.
From there, he argues that people with access to opportunity can use it to build wealth and, when they have enough, help extend opportunity to others. Moore’s case includes the possibility of starting enterprises, competing, and finding customers in developed market economies. He presents this as an argument, not a guarantee that everyone has the same chances or faces the same conditions. His larger point is that assumptions about what is possible may prevent people from recognizing openings that do exist. Opportunity depends partly on circumstances, but also on how people understand and respond to them.
Technology changes those openings. Moore describes online businesses that can reach many customers without owning all the conventional assets associated with an industry. Alibaba and Airbnb serve as examples: rather than owning the goods or properties being exchanged, they connect other people’s activity through a platform. The model can reduce the need for inventory or infrastructure and make wider reach possible. It does not mean that every business can succeed without resources, or that a platform automatically creates value. It shows how connecting people and existing assets can become a different route to scale.
The same shift affects finance. Moore points to online and digital systems as ways to move money and connect people who want to lend with people who need funding. He describes newer payment methods and cashless transactions as part of a broader move away from cash and paper. In his account, such systems can make transactions faster and open routes that do not depend entirely on traditional institutions. He also cites forecasts and country comparisons to illustrate the direction he saw at the time of writing. Those figures are period-specific examples, not current measurements or proof that every country will follow the same path.
But greater digital convenience does not guarantee equal access. In many countries or demographics across the developing world, Moore says, older people, people with limited digital skills, and poor people may be particularly vulnerable in a cashless society. In that context, homeless people can face additional barriers involving identification, credit, and access to bank accounts. A new financial channel may create options for some while leaving others with fewer practical ways to participate. That caveat matters: technology can change access, but it does not erase differences in resources, skills, or circumstances.
Cashless systems also raise questions of control. Moore reports fears that cash could be taken away and currency rendered worthless so governments could control the flow of money and increase taxes. He says he cannot yet judge whether that fear is well founded. The direction of change may be clear to him, but its consequences are not all predictable. His opening argument is therefore not simply to welcome every innovation. It is to question inherited assumptions, recognize who may be excluded, and remain alert to what greater convenience could cost.
Together, the Ferrari story and the discussion of new systems establish Moore’s starting point: money is shaped by perception, opportunity, and change. Reconsidering assumptions can help people see choices they had dismissed, while unequal access and unresolved concerns remain real limits. The chapters that follow turn from this opening frame to money’s mechanics and the methods Moore proposes for building wealth.
Chapter 2 of 13 · 5 min · Audio & textIn the app
Questioning the Money Myths
Moore challenges beliefs that can make money seem either morally suspect or beyond a person’s reach. His point is not that money solves every problem.
Chapter 3 of 13 · 7 min · Audio & textIn the app
What Money Makes Possible
Moore begins by widening the meaning of wealth. People commonly use the word for cash, savings, investments, property, and possessions.
Chapter 4 of 13 · 7 min · Audio & textIn the app
Material Life and Market Systems
Moore challenges the familiar divide between spiritual purpose and material life. Spirit, he argues, needs expression in action and form, while material things without purpose can become empty.
Chapter 5 of 13 · 5 min · Audio & textIn the app
Values Shape Money Beliefs
After discussing economic systems, Moore turns to the personal compass behind financial choices. What people value influences which opportunities they notice, which tradeoffs they accept, and what they want money to make possible.
Chapter 6 of 13 · 6 min · Audio & textIn the app
Emotions, Worth, and Responsibility
Knowing what to do with money does not always mean doing it. Moore argues that intense feelings can take over a financial choice before knowledge has a chance to guide it.
Chapter 7 of 13 · 7 min · Audio & textIn the app
From Values to Valuable Work
The previous discussion of values becomes practical here. Moore’s framework, VVKIK, connects Vision and Values to Key Result Areas, Income Generating Tasks, and Key Performance Indicators.
Chapter 8 of 13 · 8 min · Audio & textIn the app
Trust, Networks, and Contribution
Trust is an everyday economic resource in Moore’s account. Money changes hands because people expect promises to be kept, debts to be repaid, and exchanges to be fair.
Chapter 9 of 13 · 8 min · Audio & textIn the app
Leverage, Focus, and Compounding
Leverage means increasing what limited time, money, effort, or knowledge can accomplish by combining it with resources beyond your own. Moore applies it to delegation, assets, credit, systems, and partnerships.
Chapter 10 of 13 · 5 min · Audio & textIn the app
Sell by Solving Real Problems
Moore treats selling as service: learn what another person needs, offer something useful, and receive fair remuneration in return. It is a conversation about fit and exchange, not a contest of persuasion.
Chapter 11 of 13 · 7 min · Audio & textIn the app
Choose and Build the Model
Choosing a livelihood begins with deciding what kind of work fits your abilities, appetite for risk, and life outside work. Moore describes three broad paths: employee, entrepreneur, and intrapreneur.
Chapter 12 of 13 · 9 min · Audio & textIn the app
Funding and Managing Money
Once an activity is viable, the next question is how to fund it without weakening it. Moore’s options differ in how quickly they provide cash, what they cost, how much control they give away, what security they put at risk, and whether expertise comes with the money.
Chapter 13 of 13 · 7 min · Audio & textIn the app
Measure, Protect, and Grow Wealth
After discussing how money is earned and managed, Moore asks readers to make progress visible. He treats measurement as a way to move from vague worry toward a financial position that can be reviewed and changed.
Chapter 1 of 13 · 6 min · Audio & text: Money, Opportunity, and Change
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyAbout Rob Moore
Rob Moore is the author of “Money”. The book explores how people can change their relationship with money and build wealth that supports a chosen life.
Explore more books by Rob Moore